Macroeconomics often feels like a guessing game played by people in expensive suits who only check their crystal balls after the storm hits. Central banks raise interest rates, markets panic, inflation spikes, and everyday people pay the price while economists argue over theoretical models. But the Royal Swedish Academy of Sciences just threw a wrench into that lazy status quo.
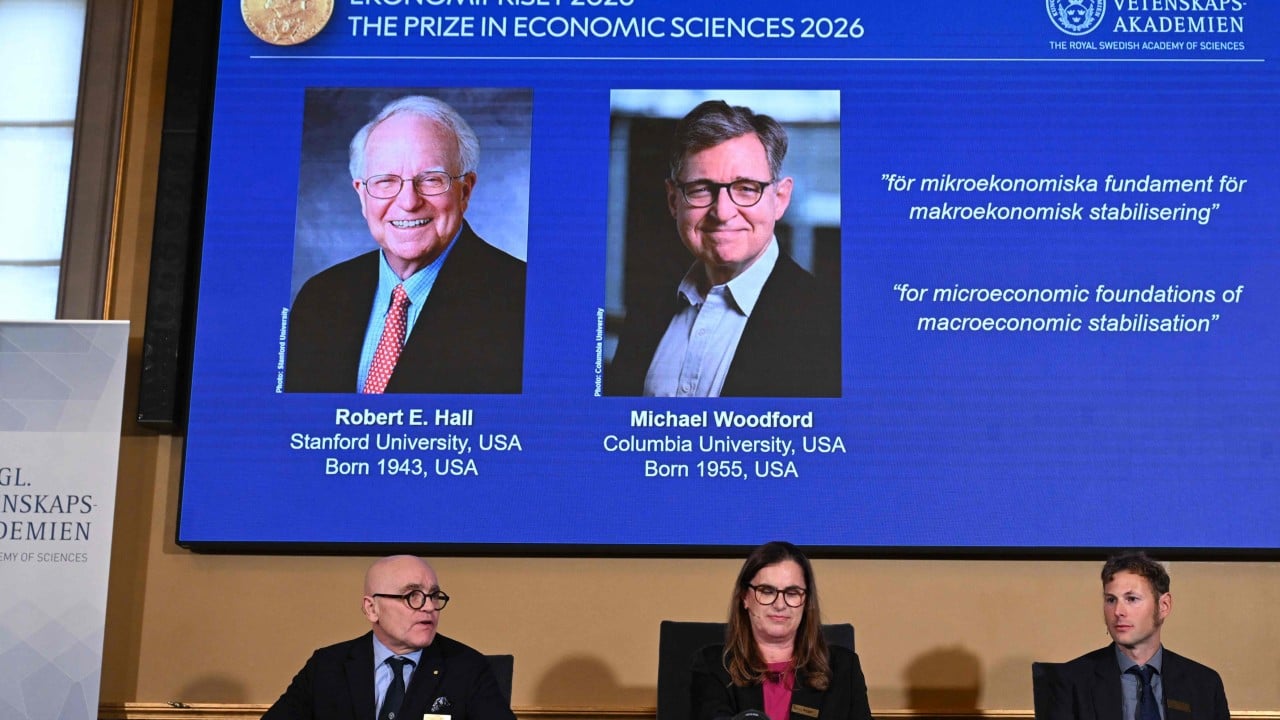
The 2026 Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel went to Robert E. Hall of Stanford University and Michael Woodford of Columbia University. If you haven't heard their names before, don't worry. Most people haven't. Yet their work shapes how central banks try to keep your job secure and your grocery bills from doubling overnight. For another perspective, read: this related article.
What Hall and Woodford Actually Did
For decades, economic theory suffered from a massive disconnect. Microeconomics looked at how individual people and businesses actually behave in the real world. Macroeconomics looked at massive, aggregate numbers like total national output and broad price indices, often treating entire populations like robots following simple mathematical formulas.
Robert E. Hall and Michael Woodford spent their careers bridging that ridiculous gap. They gave macroeconomics real-world plumbing. Similar insight on the subject has been provided by Financial Times.
Hall's work focused heavily on how unemployment behaves during recessions, showing that labor markets don't just clear instantly like textbook theory claimed. People lose jobs, stay unemployed, and consumer spending freezes because wages and hiring practices have real friction.
Woodford took things further by revolutionizing how central banks think about monetary policy. Before Woodford published his landmark research, monetary policy was mostly about staring at money supply numbers. Woodford proved that expectations matter just as much as actual interest rates. If people and businesses believe a central bank will stamp out inflation, they act differently today. That insight became the bedrock of modern inflation targeting used by the Federal Reserve and central banks across the globe.
Why Central Banks Live by Their Playbook Today
If you've ever watched a Federal Reserve press conference and heard the chair talk about "forward guidance," you are listening to a direct descendant of Michael Woodford's theories.
Central banks used to operate in total secrecy, dropping interest rate surprises on the market like bombs. Woodford's models showed that transparency and communication are actual economic tools. By telling markets what they plan to do and why, central banks shape borrowing costs long before a single rate hike takes effect.
Meanwhile, Hall's focus on stabilization policy explains why governments rush out fiscal packages during severe economic downturns. When private spending craters because everyone is terrified of losing their income, waiting for the market to fix itself takes too long. Well-timed public intervention can cushion the blow, flattening those brutal economic peaks and troughs.
The Real-World Limit of Economic Models
Let's be completely honest. Models are great until reality punches them in the face.
Even the best macroeconomic frameworks created by Hall and Woodford struggle when unprecedented shocks hit the system. Pandemics, sudden supply chain collapses, and geopolitical energy crises don't fit neatly into equations. Central banks frequently misread inflation spikes, overcorrect with rate hikes, or miss warning signs entirely.
That is why you shouldn't treat economic policy announcements as gospel. When interest rates stay high or credit tightens, your personal balance sheet absorbs the impact long before the models adjust. Understanding that these policies are based on evolving theories—rather than absolute laws of physics—helps you navigate your own financial planning with a healthy dose of skepticism.
What This Means for Your Financial Strategy
You don't need a PhD from Stanford to put these insights to work in your own life.
First, pay attention to central bank communication, but watch consumer behavior more closely. Aggregate models look at averages, but your personal financial resilience depends on your own cash flow and debt structure.
Second, expect volatility. Even with the advanced stabilization tools inspired by this year's Nobel laureates, economies still cycle. Build an emergency fund that assumes monetary policy won't save you the second a downturn hits. Keep your debt manageable when interest rates are shifting, and focus on building tangible skills that protect your earning power no matter what the broader macro numbers are doing.
Take control of your financial planning today by auditing your cash reserves and reducing high-interest debt before the next economic cycle turns.