You thought borrowing costs were finally going to drop. Think again. The central bank just shattered more than three years of monetary policy stability by pushing benchmark interest rates up by a quarter of a percentage point, landing them between 3.75% and 4%.
This marks the first rate hike since July 2023. If you're wondering why this happened right now, look no further than the energy markets. Also making headlines recently: Why The New Fed Rate Hike Changes Everything For Your Money Right Now.
The Oil Shock Driving Central Bank Action
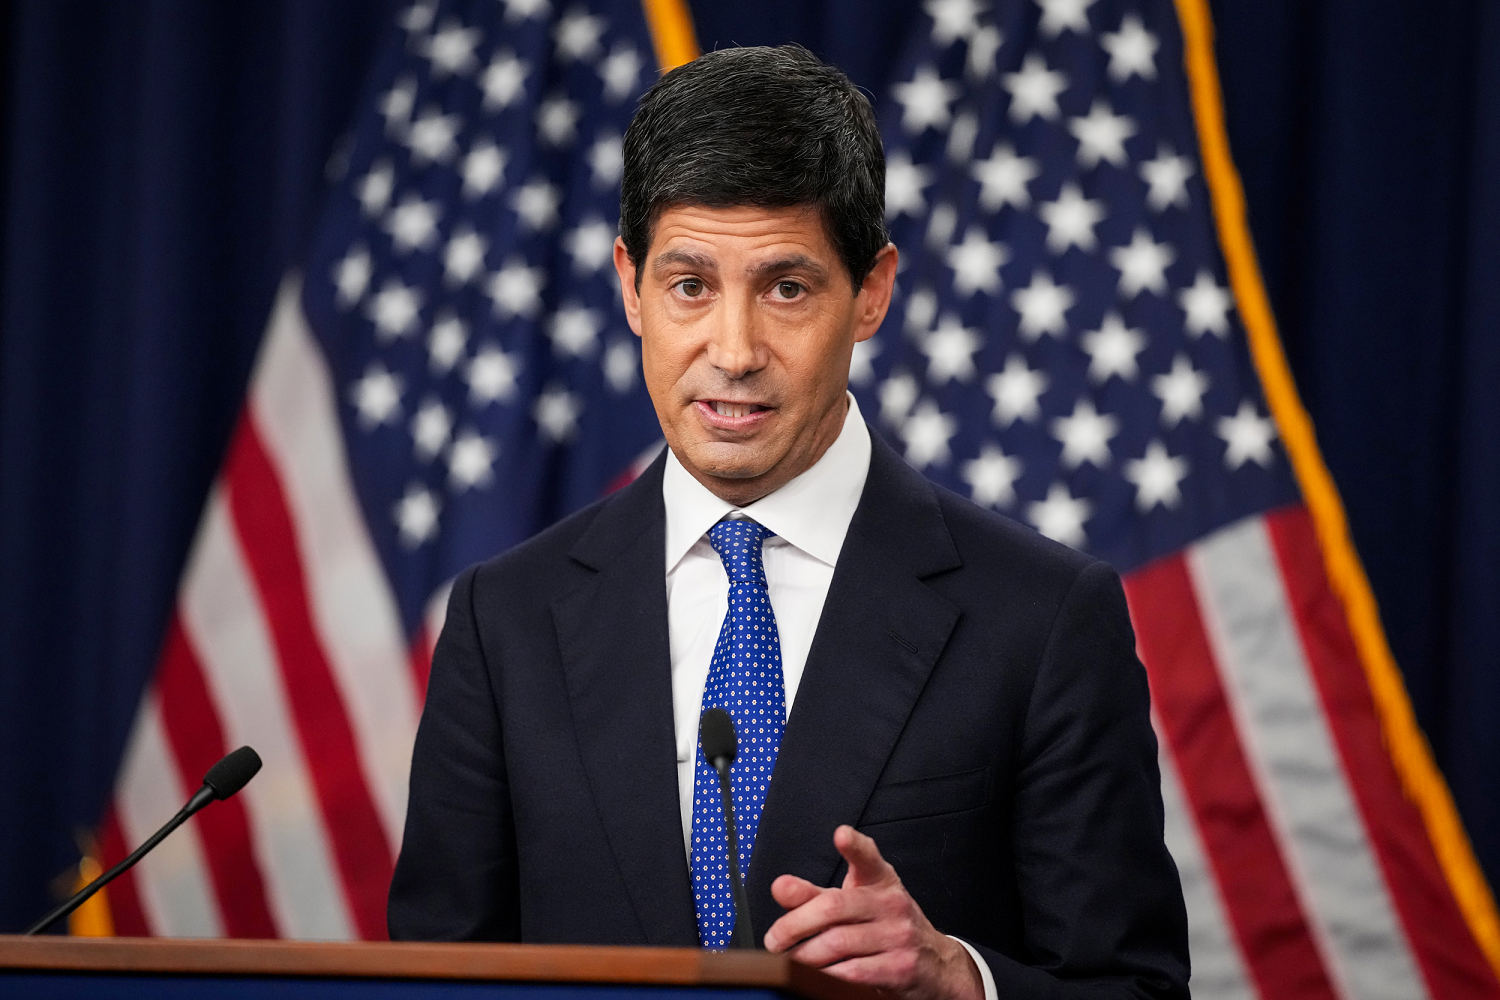
Inflation isn't fading quietly. Federal Reserve Chair Kevin Warsh made it clear that price stability takes priority over everything else. When the conflict in Iran erupted in late February, it choked the Strait of Hormuz—a crucial artery for one-fifth of global crude supplies. Add Saudi Arabia's pipeline shutdowns into the mix, and you get global crude prices surging past $105 a barrel.
Gas prices topping $4.30 a gallon across the country don't just hurt drivers at the pump. They drive up transportation expenses for groceries, clothing, and furniture. August consumer data showed inflation sitting stubbornly at 3.4%, well above the Fed's coveted 2% target. Further details regarding the matter are explored by The Wall Street Journal.
Central bankers hate persistent inflation. They acted because waiting any longer risked unmooring long-term consumer expectations.
Why the Labor Market Couldn't Save Us
For months, board members were deeply divided. Some worried that raising rates would crush an otherwise resilient labor market. After all, employers added 162,000 workers in August, and second-quarter economic growth defied gloomy recession predictions.
Yet, resilience cuts both ways. A strong job market gives consumers purchasing power, which keeps demand high while supply costs climb. The dissenters who previously voted for holds found themselves outnumbered as energy shocks filtered through the broader economy. Unanimous votes don't happen by accident; they signal a terrifying consensus that inflation was gaining too much ground.
What This Means for Your Wallet
Higher rates hit everyday finances immediately. Credit card annual percentage rates and adjustable-rate mortgages are marching upward alongside bond selloffs. If you carry debt, you're paying more every month.
On the flip side, cash isn't trash anymore. High-yield savings accounts and short-term certificates of deposit are offering competitive yields, hovering near 4%. If you've got spare cash sitting in a zero-yield checking account, you're losing money to inflation every single day.
Stop waiting for cheap money to return. Adjust your household budget, pay down high-interest credit lines, and lock in yields where you can find them.