Commercial real estate has taken a beating over the last few years, but Wall Street is starting to pick sides. While Manhattan towers struggle with stubborn vacancy rates and changing corporate habits, global financial institutions are quietly pivoting their focus eastward. Recent market analyses from firms like Morgan Stanley highlight a surprising shift in sentiment. Investors see significantly more room for capital appreciation and rental recovery in Hong Kong’s prime office hubs than in traditional New York skyscrapers.
If you are looking at where global property capital flows next, understanding this divergence matters. Let us break down why the narrative around major metropolitan workspaces is flipping.
The Reality Check on Manhattan Skyscrapers
New York commercial real estate is caught in a long transitional phase. Hybrid work models aren't just a temporary perk anymore; they are baked into corporate culture. Financial institutions and tech firms downsized their footprints drastically, leaving millions of square feet of prime Manhattan office space empty or underutilized.
Landlords of aging towers face a brutal reality. Attracting tenants back requires pouring millions into modernizing amenities, upgrading HVAC systems, and hitting strict energy efficiency standards. The math often doesn't pencil out. When debt refinancing hits at higher interest rates, property valuations drop hard. Manhattan towers carry heavy baggage right now, and the path to robust yield compression is painfully slow.
Why Hong Kong Prime Space Tells a Different Story
Hong Kong’s commercial property market went through its own severe correction, plunging from historic peaks over a multi-year slump. But that correction created an inflection point. Central district offices bottomed out earlier, and the downside risk is largely priced in.
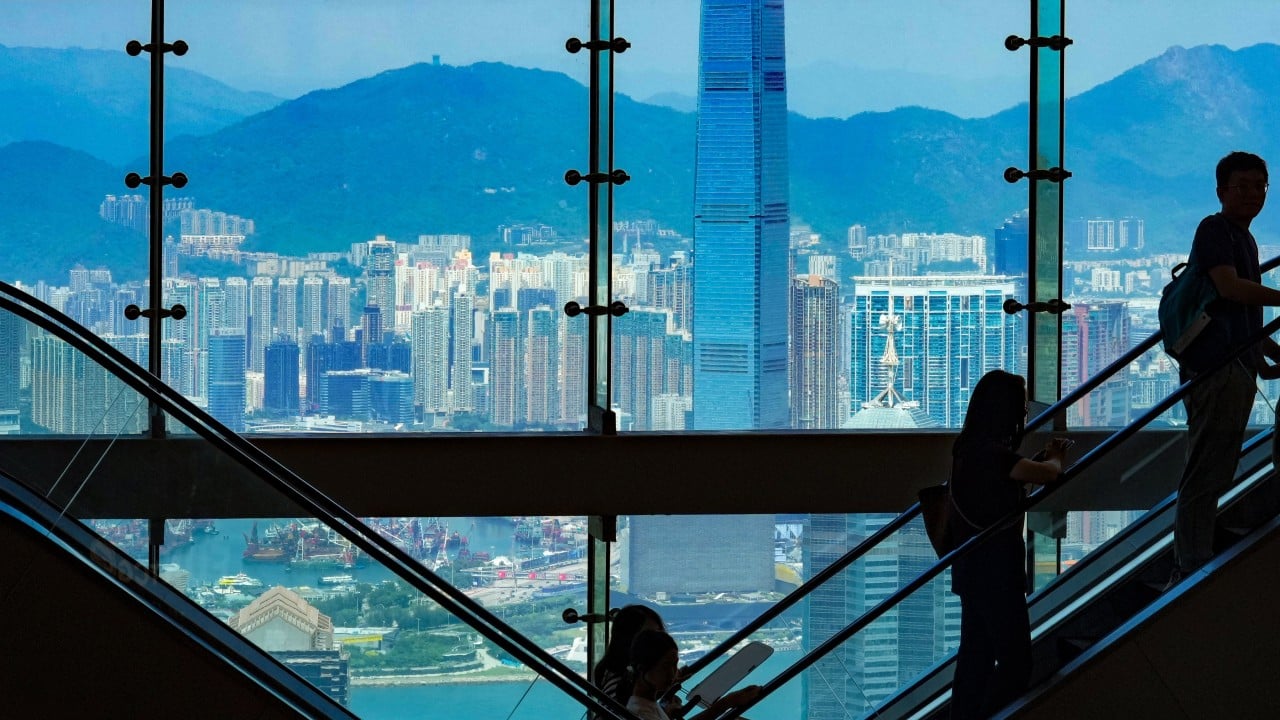
Supply constraints in Hong Kong act as a natural safety net. Unlike New York, where sprawling geography allows for continuous suburban or secondary commercial expansion, Hong Kong is physically bounded by mountains and harbor. You cannot easily build another prime Central skyscraper. When demand ticks upward, landlords hold all the cards because new competing inventory is virtually non-existent.
Vacancy rates in prime locations are stabilizing. As cross-border capital flows adapt and regional financial activity picks up steam, rental rates in core districts are finding their footing. Investors looking for a cyclical rebound find this supply-demand squeeze far more compelling than the oversupplied pipeline plaguing parts of the US.
Capital Allocation and Yield Dynamics
Institutional investors evaluate real estate through cold, hard cash-flow mathematics. Cap rates in key Asian financial hubs have adjusted to a new interest rate reality faster than many Western counterparts.
When you compare a New York tower facing massive tenant concession packages—where landlords pay for tenant build-outs and offer months of free rent just to secure a signature—with a recovering Asian market where rental concessions are shrinking, the upside potential becomes clear. Hong Kong landlords are beginning to regain pricing power on leases expiring through late 2026 and 2027.
Property shares on the Hong Kong Stock Exchange already reflect this shifting tide, rallying as analysts upgrade sector forecasts. Smart money follows the bottoming process, and Hong Kong has crossed that threshold ahead of Manhattan.
What This Means for Global Property Strategies
Real estate is hyper-local, but global macro trends dictate where institutional portfolios place their bets. You cannot apply a blanket strategy across every major financial center.
If you manage commercial assets or follow institutional capital trends, stop treating all downtown cores the same way. New York towers require patience, deep pockets for massive retrofitting, and a long-term bet on Manhattan’s cultural resilience. Hong Kong offices offer a sharper cyclical recovery play driven by acute geographical scarcity and compressed valuations.
Keep a close eye on leasing velocity in Central over the next two quarters. The market is moving past the worst of the downturn, and the upside surprise is already underway.