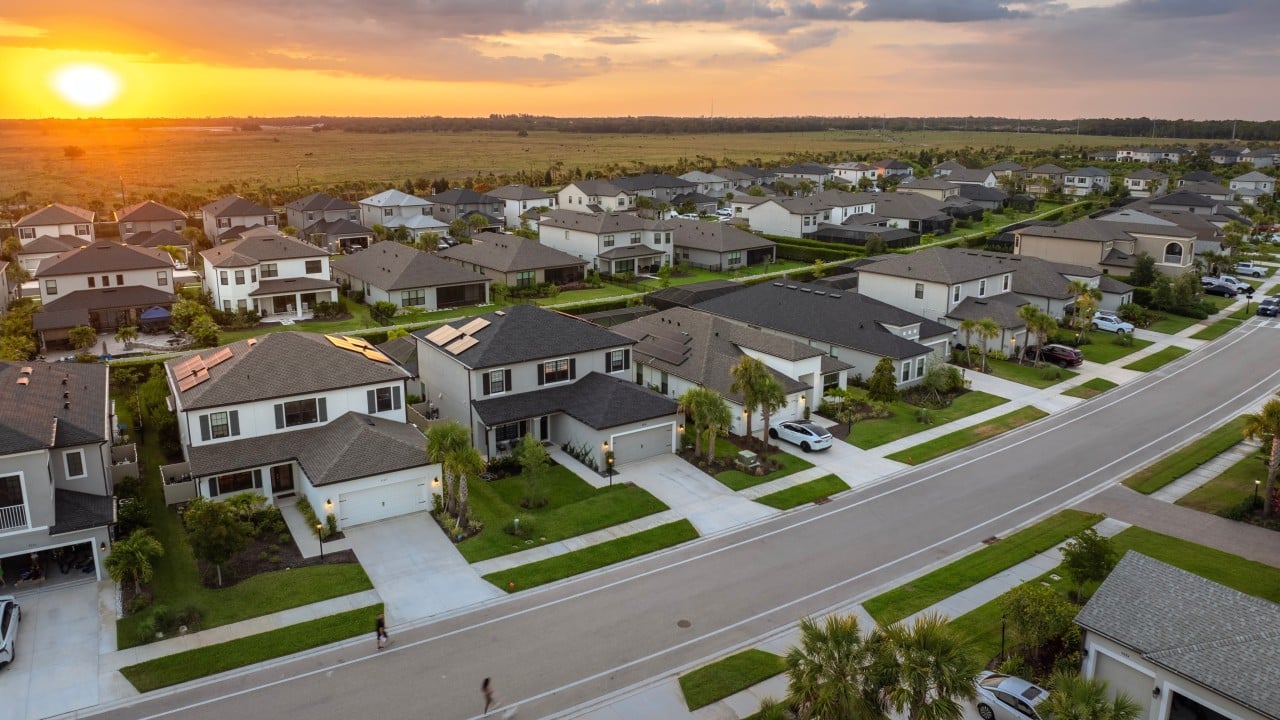
You thought borrowing costs couldn't get any worse, but the 30-year fixed mortgage rate just punched past the dreaded 7% threshold.
According to Freddie Mac data, the average 30-year mortgage climbed to 7.03%. That marks the highest level since January 2025 and a bitter pill for anyone trying to purchase real estate during Donald Trump's presidency. Just months ago, buyers caught a brief glimmer of hope when rates dipped below 6%. Those hopes are gone. Bond yields are surging, inflation is sticky, and the housing market is bracing for another deep freeze.
If you are hunting for a home right now, you need a reality check.
What Triggered the Spike
Let's clear the air. The Federal Reserve doesn't directly set mortgage rates, but its recent policy moves definitely cast a long shadow. Following sticky inflation pressures and energy shocks tied to conflicts in the Middle East, the central bank recently pushed benchmark interest rates higher for the first time since 2023.
Bond markets reacted instantly. The 10-year U.S. Treasury yield—the real benchmark that mortgage lenders track—climbed aggressively, pushing borrowing costs upward for five consecutive weeks.
Energy prices didn't help either. Spiking gasoline and diesel costs are driving up everyday goods, which means inflation refuses to cool down. When prices rise across the economy, lenders demand higher yields to protect their returns. That means you pay more every single month.
The Psychological Toll of the 7 Percent Mark
Economics is half math and half psychology. Crossing 7% isn't just a number change on a spreadsheet. It acts as a heavy mental barrier that scares buyers away.
Think about the math for a second. If you buy a median-priced home today compared to locking in a rate earlier this year when numbers brushed near 6%, you aren't just paying a bit extra. You are committing to thousands of dollars more in interest over the life of the loan. That difference translates directly into lower purchasing power. A house that fit your budget in February might now require a monthly payment that stretches your finances to a breaking point.
Real estate analysts point out that many sellers are also staying put. Why would anyone trade a 3% mortgage rate from the pandemic era to buy a new home at 7%? This "lock-in effect" keeps inventory tight, preventing prices from crashing even as demand slows down.
How to Navigate a Frozen Market
Waiting around for rates to magically plummet back to historical lows is a losing strategy. If you need to buy a home, you have to approach the market with a completely different playbook.
First, stop obsessing over the headline rate. Smart buyers focus on what they can control, which is the purchase price and their loan structure. You can always refinance later if rates drop, but you can't renegotiate the price of the house after you sign the deed.
Second, look into adjustable-rate mortgages or seller concessions. Many homebuilders and private sellers are offering rate buydowns to entice hesitant buyers. Take advantage of those credits. They save you real cash during the critical first few years of homeownership.
Finally, clean up your personal balance sheet. Lenders are tightening standards as economic uncertainty grows. Paying down high-interest credit card debt and boosting your credit score will net you a better tier of pricing, even in a hostile lending environment.
The housing market is tough, but ignoring reality won't get you the keys. Adjust your budget, look for motivated sellers, and stop waiting for a bailout that isn't coming.